I had my thumb over the January mortgage transfer when I read the sentence in my parents’ trust that said I’d been left out on purpose. I was parked at a pipeline site near Truman, Arkansas, still wearing my work gloves, and the phone screen had a crack across the little bank icon. I read the line once, then again, because it was plain enough that I thought I must have missed something above it.
I’m Joel. I’m thirty-seven, and I weld pipe for a living out of Jonesboro.
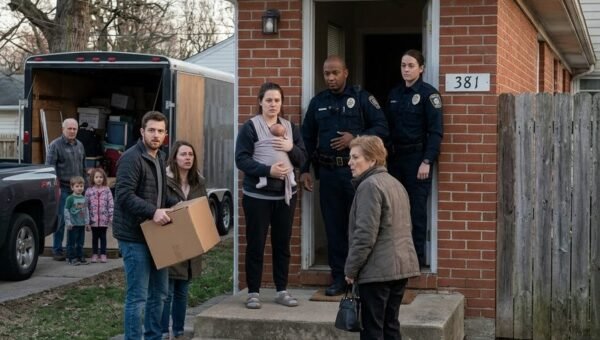
My parents, Dale and Marlene, live outside Bono in a brick ranch with fifteen acres and a metal workshop behind it. My younger brother, Nick, runs an auto repair business out of that workshop. That’s the part of the story people usually understand right away. The other part took me longer.
I’d been sending my parents $1,850 on the first of every month for six years. Seventy-two payments, if I’m counting right. That’s $133,200, before the insurance bill and a few other things I covered when they came up short. I didn’t keep a spreadsheet at first. I used to think keeping track would make it feel like a business deal, and I didn’t want to be that son.
I’m telling this as plainly as I can because I know how it sounds when I say I paid their mortgage for six years and didn’t ask what I’d get back. I wasn’t promised the house. I never had a written agreement. I did think I was helping my parents keep a home they’d eventually leave to both their sons. I guess I thought that without ever making them say it.
Dad lost his maintenance job with the school district in 2019. He’d been there long enough that everybody figured he’d work until he was ready to quit, but his back was bothering him and the district offered him an early retirement package.
It cut his pension more than he’d expected. By December, my parents were two payments behind on the mortgage.
Mom called me from the kitchen. I could hear the microwave beeping in the background, which is a dumb thing to remember, but I remember it. She said they were trying to catch up and asked whether I could cover one payment. I had money saved for a down payment on a little house of my own. I said I could help for a month or two.
Mom hugged me the next time I went over. She called me “the steady one,” then said Dad would find something soon.
I believed her. Dad had fixed things for half the people in Bono at one point or another, and he wasn’t the type to sit around if there was work he could do. But the jobs he found were short, and his back kept getting worse.
Three months later, I set up the automatic transfer. It seemed easier than remembering the date, and it meant Mom didn’t have to call me when the payment was due. After that, the money just went out on the first. Nobody thanked me every month. Nobody asked if I still could. I didn’t bring it up, either.
That’s not me making them sound cold. They had other things going on, and I didn’t want to be the son who sent an invoice with every family dinner. Still, once in a while I’d look at my bank account after payday and think, well, there goes another month. Then I’d put my phone away and get back to work.
Three years in, I found a small house I liked. Nothing fancy. Two bedrooms, old siding, and a kitchen where the drawers stuck if you pulled them too fast. I’d been saving for years, and I could make the down payment if I stopped sending money to my parents for about eight months.
I brought it up at dinner, trying to sound casual. Mom lowered her fork and said they couldn’t go eight months without help. Then she mentioned I didn’t even have a girlfriend, like that meant I didn’t need a place of my own. I didn’t say anything useful. I just stared at the little tear in the tablecloth near my plate and said I’d think about it.
I let the house go. I still think about it sometimes, which is embarrassing because it wasn’t even a great house. I just liked the idea of having one door that nobody could tell me I was selfish for closing. The mortgage payment stayed on autopay, and I told myself it wasn’t forever.
Nick’s business was having a rough patch around then. He moved his auto repair work into Dad’s workshop, which made sense because it had room for trucks and a good concrete floor. Dad gave him the keys. Nick put his own name on the door, then started bringing in more vehicles. Before long, he had a lift installed that cost him around $9,000.
I remember Dad showing it to me. He was proud of the thing, and I was happy for him. The workshop had been his place for years. He’d spent evenings in there fixing lawn mowers and old trucks, usually with the radio tuned to a station that played the same Johnny Cash songs every Sunday. Now Nick was making a living there. It looked like a good fit.
I never asked Nick to help with the mortgage. That part was my choice, too. I figured he was putting money into the business and trying to get it going, while I had steady work. But he knew I was paying. Mom had said so right in front of him more than once, and he’d made a joke about me being the bank of the family. I laughed like it was funny.
When the homeowners insurance escrow came up $2,300 short, I paid it. Mom said she’d pay me back when they got their tax refund. I told her not to worry about it. She didn’t bring it up again, and I didn’t ask. I did, however, remember that number. I don’t know why that one stuck when the monthly payments blurred together.
Dad handed Nick the keys to the workshop and the property gate one afternoon. It wasn’t some ceremony. He just passed them over while I was there and told him to make a copy. Mom smiled and said someday the place would be in good hands. I assumed she meant Nick’s business. I didn’t think it meant the house, the land, and everything else too.
I kept paying. That’s the part I can’t make sound smart. I had chances to ask what their plans were. I had chances to say I couldn’t keep doing this forever. Instead, every month I told myself I was helping them get through a tight stretch. Then the next month came. The money went out.
Last December, Dad asked me to get an insurance renewal paper from the hallway closet. I was home because I’d stopped by after work, and he was in the living room with a heating pad on his back. The papers were in a folder with “house” written across it in Mom’s handwriting. I found the renewal notice and another packet behind it.
It was a legal packet from a law office in Jonesboro. I’m not proud of what I did next. I looked through it. I could’ve brought the whole folder to Dad and asked him what it was, but I opened it and read it first. I told myself it was their house and they’d asked me to get a paper, so I had a reason to see what was there.
The trust was signed November 12. It put the house, all fifteen acres, the workshop, and everything inside it in Nick’s name after my parents died. It named him as trustee. I read the same pages more than once, looking for some note about me, some part where I’d misunderstood. There wasn’t one.
On page five, one sentence sat by itself. “We have intentionally made no provision for our son, Joel.” I read it out loud in the empty hallway. It sounded like something from a form. I put the papers back in order and carried Dad the insurance renewal like nothing had happened.
After I left, I sat in my truck in the driveway with the engine off. I kept thinking of all the firsts of the month. $1,850, over and over. The house I’d let go. The extra insurance bill. And the mortgage itself had a five-year balloon payment coming due January 31. They were going to need help with that too.
I didn’t call them that night. I went home, opened my bank app, and canceled the automatic transfer. The bank asked me to confirm, so I did. I stared at the screen for a while after it said the transfer was canceled. It was a small button. It didn’t feel like a small thing.
Two weeks later, on January 16, Mom texted that I was late that month. No hello, no question about work, just the payment. I wrote back, “Ask Nick. It’s his house.” I didn’t add anything else. I could’ve said I was sorry or explained how I’d found the trust, but I wanted her to have to ask me first.
She called four times that evening. Dad texted me to call her back. I didn’t. I had my reasons, but I also knew I was making her sit with it. Maybe I wanted that. I don’t love admitting it, but I was angry enough that I wanted the first uncomfortable night to belong to them.
A week later, Mom came to my rental house with Nick and a manila folder. She sat down at my kitchen table like we were there to talk about a bill. Nick stayed standing for a minute, then pulled out a chair. Mom said Delta Ridge Bank could refinance the mortgage over thirty years, but the loan officer wanted another borrower with a steady income.
Me. She said I was already paying the mortgage, so this would only put my name on some paperwork. I asked who would get the property if my parents died. Mom said that was a separate issue. Nick said the trust was just legal paperwork and wasn’t personal. I looked at him and said, “It literally names me, Nick.”
Mom started talking about how Nick needed something secure because his business income went up and down. I asked why that meant I should take on the debt while he got the property. She said it wasn’t like that. I asked how it was different. She didn’t answer.
I said no. No to co-signing, and no to paying January’s mortgage. Mom warned me that Dad could lose the house. I told her Dad had signed the trust. It came out calmer than I felt, but it also came out sharper than I meant it to. Mom packed her folder and said we had a bank appointment on January 29 at two. She was sure I’d change my mind.
After they left, I saw the folder still on the table. I shouldn’t have opened it. I did anyway. My name was already typed into the loan application as a co-borrower. My job, employer, and phone number were filled in. There was a yellow sticky note with an arrow pointing to the empty signature line.
Nick came back later by himself. He had a twelve-pack of the soda I used to drink when I was a teenager. I don’t know if he brought it because he thought it would soften me up or because he actually remembered I liked it. He said once I signed, Mom and Dad could keep the house and he could keep the shop. Everybody would be comfortable for the next thirty years.
I told him I wasn’t signing. He said it wasn’t fair to leave our parents with nowhere to go. I reminded him it was their house and they had chosen who got it. He rubbed his thumb over the soda can, the way he used to when he was trying to find something to say. Then he left the pack on my table and went home.
The loan officer called me the next day. His name was Gerald Haskins. He said he needed my tax returns and signed authorization before he could run my credit. I told him I hadn’t agreed to be on the loan. There was a pause, then he said he understood and that he’d noted it.
While we were talking, he mentioned the application had been open since November 10. I stopped walking through the grocery store parking lot. November 10 was two days before my parents signed the trust leaving the property to Nick. I asked Gerald to repeat the date. He did.
I asked whether I was listed as a borrower then. He said the file showed me as a proposed co-borrower, but he couldn’t tell me more without the right authorization. I said I’d be at the bank on the twenty-ninth. Then I called Mom. She didn’t pick up. I didn’t leave a message.
That night, I got out the copies I’d taken of the trust and put them in a folder. I kept thinking about the date. Two days before they signed it. I wondered whether they’d talked about refinancing with the bank first and then changed the trust, or whether they’d already decided I’d take on the payment while Nick got the place. I couldn’t know. I didn’t want to guess. I also wasn’t going to sign anything until I knew what they’d told the bank.
January 29, I went to Delta Ridge with the trust in my folder. Mom was there already. Dad sat beside her, his hands on his knees. Nick leaned back in his chair like the meeting was just another thing I’d been asked to fix. Gerald had the loan papers ready.
Before he could explain them, I put page five of the trust on his desk and read the sentence about no provision for me. Mom started to say that the trust wasn’t the reason for the meeting. I asked Gerald who would inherit the house and land if my parents died. He said the trust named Nick. Then I asked who would owe the money if I signed.
Gerald said I’d be a co-borrower and responsible for the full balance with my parents. I looked at Mom, then at Nick. “So Nick gets the property, and I get the debt.” Gerald paused. “As the documents are written now, yes.”
Mom began to protest. I turned back to Gerald and asked who was listed as the primary contact on the application. He looked at the monitor for a few seconds, then turned it toward us. I could see my name under proposed co-borrower, and Nick’s name as the contact.
Gerald opened the file notes. He read a line from November 10, then stopped and asked if he should read it aloud. I said yes. Mom reached for the folder, but I put my hand on it. Not hard. Just enough to keep it where it was.
The note said Nick had told the bank I was expected to co-borrow because I was already making the mortgage payments. It also said I hadn’t been contacted yet, and the family would discuss it after the trust paperwork was completed. Gerald glanced at my parents and added that no loan had been approved and no signature had been given.
Nobody spoke for a few seconds. Then Nick said he’d only been trying to get the bank to hold the rate. Mom said they never meant to hide anything from me. I asked why the bank had been told I was expected to sign before anybody asked me. Dad rubbed his hands together and said they thought I’d understand once we all sat down.
I said I understood the numbers. I understood the trust. I understood what they wanted me to sign. I didn’t yell. I wasn’t trying to punish them by making a scene. I just said I wasn’t part of the loan and asked Gerald to take my name off the application.
Gerald said he could mark me as declined and close the file unless my parents found another borrower. He asked whether I wanted him to do that while we were all there. I said yes. Mom looked at me like I’d moved the house out from under her, but I hadn’t. It had never been mine.
The bank closed the application with my name on it. My parents still had to deal with the balloon payment, and I don’t know what they worked out after that. I didn’t ask Nick to take over my old payments, either. It wasn’t my loan, and I wasn’t going to trade one quiet assumption for another.
I went home with the trust copy in my folder. The twelve-pack of soda was still on my kitchen table. I put it in the fridge because I couldn’t think of anything else to do with it. A few days later, I drank one while standing by the open refrigerator door.
My parents haven’t asked me to send money since. They haven’t said they’re sorry, either. Dad called once about a tool he thought I’d left at the workshop. I told him I hadn’t. We talked for maybe a minute. He said he’d call again, and I said okay.
I still have the folder with the trust and the copy of the application notes. I don’t look at it every day. I keep it in the same drawer as the old house listing I saved when I thought I might buy that little place. The drawer sticks unless I lift it slightly.
The bank file said I was expected to sign. It didn’t say I had. I suppose that’s the part I’m left with. My name was on the page before I ever saw it, and now it isn’t. I still don’t know whether that was the line they meant to cross, or the line they thought I wouldn’t notice.